Navigating Workers’ Compensation Claims in 2026: A Step-by-Step Guide to Benefits, Legal Rights, and Settlement Calculations
Sustaining an on-the-job injury or occupational illness can immediately disrupt your physical health, daily livelihood, and family finances. Across the United States, managing workers’ compensation claims is the legal mechanism established by state statutes to guarantee prompt medical care, vocational rehabilitation, and partial wage replacement for injured personnel. However, meeting strict state reporting deadlines, calculating Average Weekly Wages (AWW), and negotiating fair lump-sum settlements require a clear understanding of your legal rights.
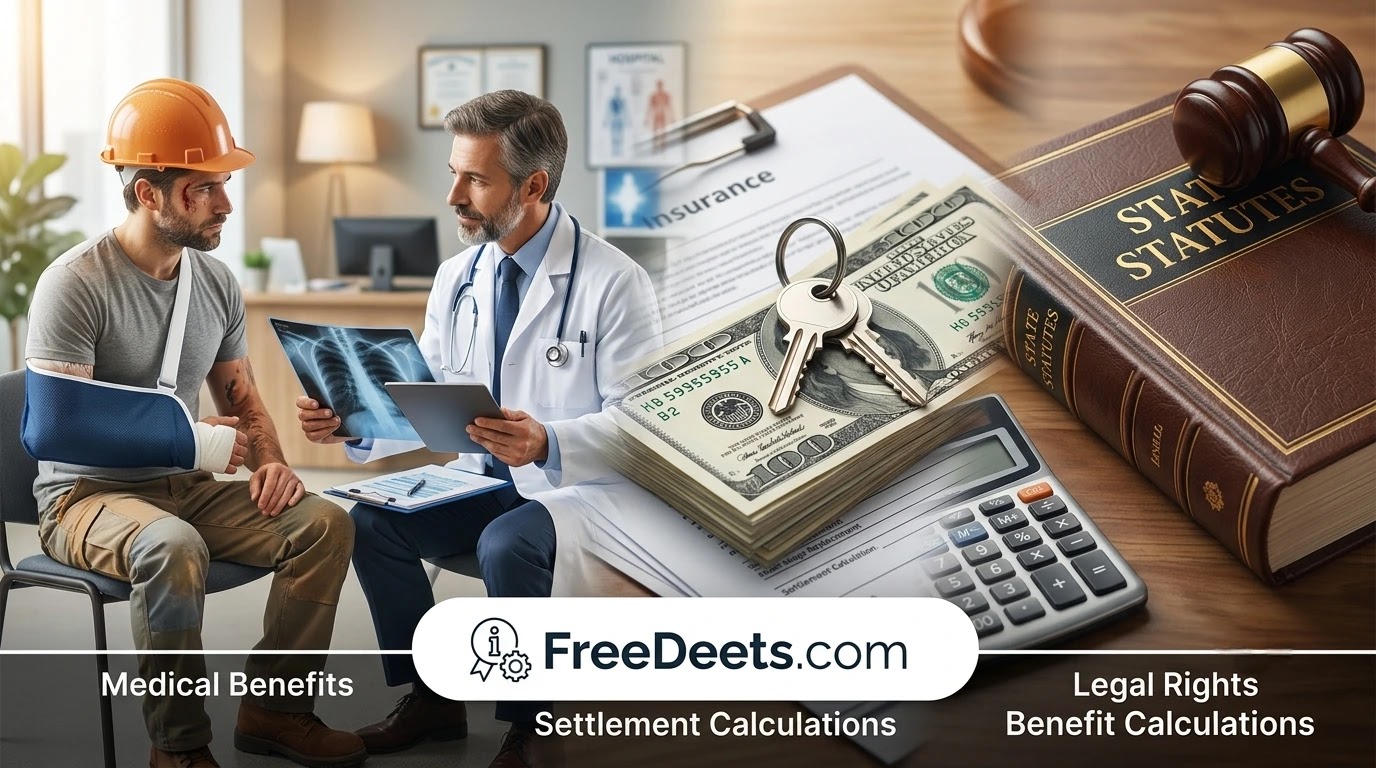
The system operates on an established legal compromise. According to statutory oversight principles enforced by the U.S. Department of Labor Office of Workers’ Compensation Programs (OWCP), workers’ compensation functions as a no-fault administrative system. Employees receive guaranteed medical care and wage loss benefits regardless of whether they or their employer caused the accident, in exchange for forfeiting the right to file civil negligence lawsuits against their employer in standard courtrooms.
Core Takeaway for Injured Workers
Missing state notification deadlines (often within 14 to 30 days of injury) is the number one reason legitimate workers’ compensation claims are denied by insurance adjusters. Immediate written documentation is essential.
1. How the No-Fault Workers’ Compensation System Operates
To qualify for statutory benefits, an injured worker must prove that their condition arose “out of and in the course of employment.” This legal standard covers two main types of workplace harm:
- Traumatic Acute Accidents: Sudden physical events such as slips, falls from scaffolding, machinery entanglements, or motor vehicle crashes while driving commercial company vehicles.
- Cumulative Trauma and Repetitive Stress: Progressive physical wear developing over time, such as carpal tunnel syndrome, chronic lumbar disc herniations, or occupational hearing loss from machinery.
- Occupational Diseases: Respiratory illnesses, chemical toxicities, or systemic health conditions caused by prolonged exposure to airborne toxins, asbestos, or industrial chemicals at job sites.
2. The 4-Step Protocol for Filing Workers’ Compensation Claims
Following strict procedural steps immediately after an accident preserves your right to full statutory benefits:
- Seek Immediate Authorized Medical Treatment: Inform the emergency room staff or treating physician that your injury occurred at work. This ensures hospital records explicitly link your medical condition to your employment duties.
- Provide Formal Written Notice: Notify your employer or HR representative in writing within statutory state deadlines (typically between 14 and 30 days). A casual verbal comment to a coworker or floor supervisor does not satisfy legal notice requirements.
- File the Official State Claim Form: Your employer must supply an official claim document (such as California’s Form DWC-1, New York’s Form C-3, or Texas Form DWC-041). Complete the injured employee section accurately, documenting the date, exact time, job location, and specific physical mechanisms of injury.
- Maintain a Detailed Medical and Financial Log: Keep copies of work restriction slips, physical therapy logs, mileage records to medical facilities, out-of-pocket prescription receipts, and dates of missed shifts.
3. Workers’ Compensation Benefit Categories & Wage Calculations
Benefits provided under workers’ compensation claims generally fall into four statutory categories designed to keep injured employees solvent during treatment:
Medical Coverage (100% Statutory Paid)
All reasonable and necessary medical treatments related to your work injury are fully covered with zero patient copays or deductibles. This includes diagnostic MRI scans, surgery, prescription medications, assistive mobility hardware, and travel mileage reimbursement for doctor appointments.
Temporary Total Disability (TTD) Benefits
If an authorized medical doctor places you on off-work status while recovering, you receive tax-free Temporary Total Disability payments. In most US states, TTD is calculated at 66.67% (two-thirds) of your pre-injury Average Weekly Wage (AWW), up to maximum weekly statutory caps set by state labor commissions.
If your gross earnings averaged $1,200 per week during the 52 weeks prior to injury, your weekly TTD benefit is approximately $800.04 tax-free per week ($1,200 × 0.6667), subject to regional state maximum benefit ceilings.
Permanent Partial Disability (PPD) & Impairment Ratings
Once your recovery reaches Maximum Medical Improvement (MMI)—meaning your condition has stabilized and is unlikely to improve further—a qualified medical evaluator assigns a permanent physical impairment rating. This percentage is multiplied against statutory state schedules to determine monetary disability settlements.
| Benefit Type | Standard Calculation Formula | Tax Status | Payment Duration |
|---|---|---|---|
| Temporary Total (TTD) | 66.67% of Average Weekly Wage | Non-Taxable | Until MMI or return to light-duty work |
| Temporary Partial (TPD) | 66.67% of wage difference during light duty | Non-Taxable | Until full wage earning capacity is restored |
| Permanent Partial (PPD) | Impairment % rating × Statutory schedule | Non-Taxable | Lump-sum or scheduled weekly installments |
| Vocational Retraining | Tuition vouchers / skill development funds | Direct Tuition Aid | When physical limits prevent past job duties |
4. Common Claim Denials and the Appeals Process
Insurance claims adjusters actively investigate workplace claims to limit payouts. Common defenses cited in denial notices include:
- Pre-Existing Injury Allegations: Insurers argue that back or joint issues resulted from aging or non-work activities. However, under established state laws, an on-the-job aggravation or acceleration of a pre-existing medical issue remains fully compensable.
- Worker Misclassification: Employers classifying staff as 1099 independent contractors to evade workers’ comp mandates. Under labor rules enforced by the Occupational Safety and Health Administration (OSHA), actual workplace control determines true employee status.
- Disputed Witness Statements: Lack of eyewitness testimony during unwitnessed accidents. Reporting the injury immediately to your supervisor prevents adjusters from questioning credibility.
If your claim receives a formal Notice of Denial, you possess the legal right to file an administrative appeal before your state Workers’ Compensation Appeals Board or request a hearing before an Administrative Law Judge.
5. Structure of Lump-Sum Settlement Agreements
When concluding a complex claim, insurance carriers often offer lump-sum settlements. These fall into two standard structures:
- Compromise and Release (C&R): Closes your entire claim—including all future medical care rights—in exchange for a single, large lump-sum payout. This structure is common when injured workers want to manage their own healthcare through private doctors.
- Stipulated Finding & Award: You agree on a specific permanent disability rating percentage paid over bi-weekly installments, but your right to have future medical treatments paid by the insurance carrier remains open for life.
Frequently Asked Questions About Workers’ Compensation Claims
Can my employer fire me for filing a workers’ compensation claim?
No. Federal and state labor statutes explicitly prohibit employer retaliation. Firing, demoting, cutting hours, or harassing an employee for reporting an injury or filing a claim is illegal, exposing the employer to substantial wrongful termination and civil penalty lawsuits.
Are workers’ comp wage replacement benefits taxable?
Under IRS code Section 104(a)(1), workers’ compensation disability payments received for occupational injuries or illnesses are fully exempt from federal, state, and local income taxes.
Can I see my own personal doctor for a work injury?
Doctor selection rules depend on state laws. Some states allow you to select any licensed physician, while others require you to choose from an employer-designated Medical Provider Network (MPN) for initial appointments. Checking state regulations ensures treatment remains covered.
Core Takeaways for Injured Personnel
- Submit written injury notification within state statutory windows (14 to 30 days).
- TTD benefits replace roughly two-thirds of your pre-injury Average Weekly Wage tax-free.
- Consult an experienced workers’ compensation attorney if facing bad-faith claim denials.
Conclusion
Experiencing an on-the-job injury is physically and emotionally challenging, but the workers’ compensation system is designed to provide immediate medical treatment and wage security while you recover. By adhering strictly to reporting deadlines, maintaining comprehensive documentation, and understanding your statutory rights, you can navigate workers’ compensation claims successfully and secure the financial benefits you deserve.